

Feeling the sting of high credit card interest? If you've ever looked at your statement and wondered why the APR is so high, you're not alone. It's a market reality, shaped by big economic forces and a card issuer's need to price for risk—it's not just about your personal spending habits.
Understanding why your rates are stubbornly high is the first real step toward reducing your credit card interest and taking back control of your finances.
Why Are Credit Card Interest Rates So High?
It can feel personal, but that double-digit interest rate on your statement is a cold, hard business decision. At its core, a high APR is the lender's way of managing risk. They're pricing the loan—your credit card balance—based on how likely they think you are to pay it back on time.
Several key factors feed into this calculation, and it all starts with your own financial picture.
- Your Credit Score: This is the big one. A lower score signals higher risk to lenders, and they'll charge you a higher APR to compensate for that risk.
- Payment History: A solid track record of on-time payments shows you're reliable, which can help you qualify for better rates down the road.
- Credit Utilization: If you're constantly maxing out your cards, lenders see that as a sign of financial strain. That translates directly to a higher interest rate.
The Disconnect Between Federal Policy and Your Wallet
You’d think that when the Federal Reserve lowers its benchmark interest rates, your credit card APR would drop, too. Right? Unfortunately, it's not that simple, and the reality is rarely in the consumer's favor.
Credit card issuers are lightning-fast when it comes to raising your rates when the Fed tightens policy. But when the Fed cuts rates? They are notoriously slow to pass along those savings.
This creates a huge gap between what's happening in the national economy and the interest charges hitting your monthly statement. For instance, after the Federal Reserve implemented three separate rate cuts, the average credit card interest rate for accounts carrying a balance barely moved, dropping from 22.83% to just 22.30%.
That tiny decrease of only 0.53 percentage points shows just how issuers protect their profit margins, leaving consumers to shoulder the burden of high-interest debt. You can dig deeper by exploring the analysis of credit card rate forecasts.
This one-way relationship means you can't just sit back and wait for the economy to lower your interest burden. You have to be proactive to reduce your credit card interest, no matter what the market is doing.
Market Realities and Business Models
Beyond your personal risk profile, credit card rates are also a product of the issuer's business model. Let's be honest: the interest paid by people who carry a balance is a massive revenue stream for these companies.
That income funds everything from their day-to-day operations and fraud protection to those juicy rewards programs and sign-up bonuses everyone loves.
Ultimately, high rates are a market standard, not a personal failing. Knowing this shifts the power back to you. It’s not about accepting the status quo; it’s about understanding the game so you can play it smarter. The next sections will show you exactly how to do that.
Actionable Steps to Lower Your Current APR
Alright, now that we’ve covered why interest rates are so stubbornly high, it’s time to fight back. You have more leverage than you think when it comes to reducing credit card interest rates. The secret is to be prepared, persistent, and strategic, and it all starts with a simple phone call.
A lot of people are hesitant to pick up the phone, but you'd be surprised how often a direct request actually works. Your card issuer wants to keep good customers, and if you have a solid payment history, they have a real incentive to work with you.
Preparing For The Negotiation Call
Don’t go into the conversation cold. A little prep work beforehand goes a long way and will seriously boost your confidence and your odds of success.
Before you dial the number on the back of your card, get these details handy:
- Your Account History: Know exactly how long you’ve been a loyal customer and make sure your on-time payment record is clean. Loyalty is a great bargaining chip.
- Your Current Financial Picture: Be ready to briefly mention your income and your credit score, especially if it’s gone up recently.
- Competitor Offers: Have you gotten any 0% APR balance transfer offers in the mail? Mentioning a specific offer from a rival company can light a fire under them.
When you have this info ready, you're arguing from a position of strength. You're not just asking for a favor; you're reminding them that you're a valuable customer who has other options.
This decision tree gives you a visual on how to think through tackling a high APR, based on where you're at financially.
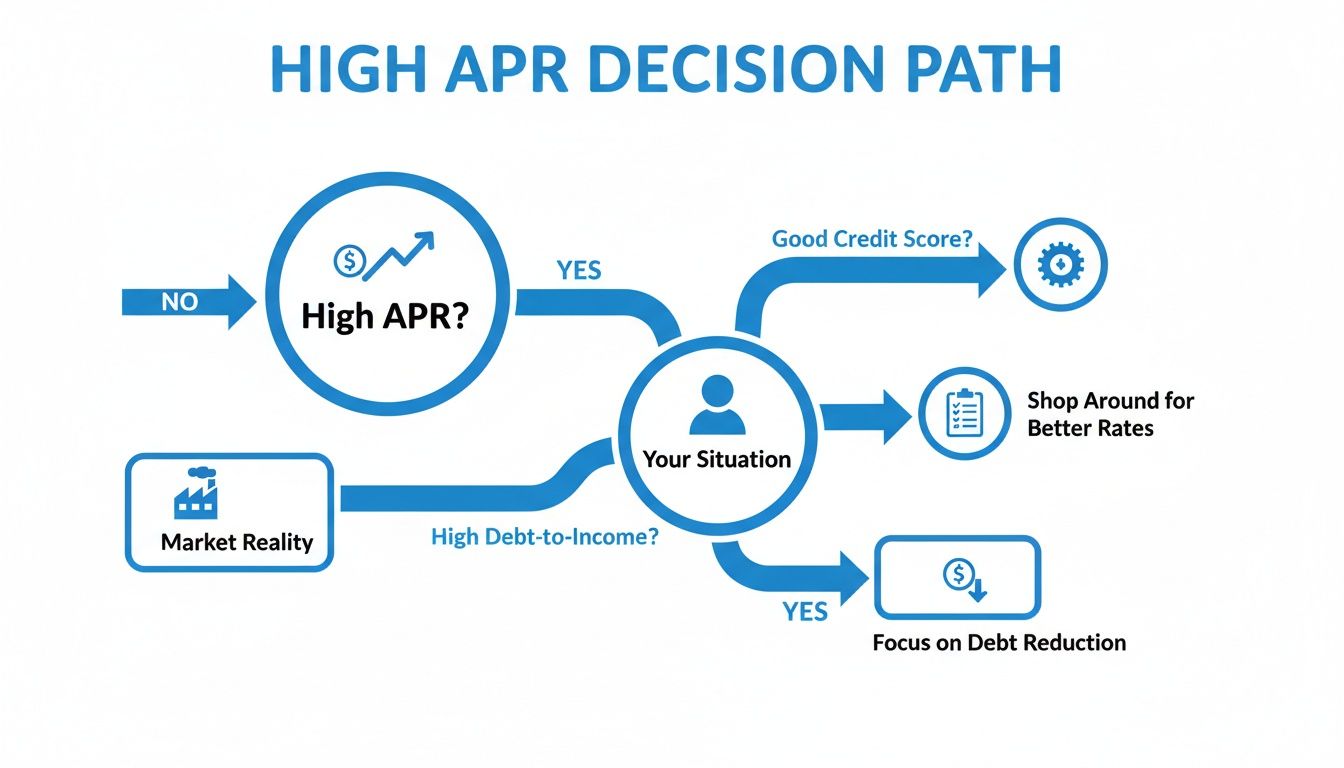
As the flowchart shows, while big-picture market conditions matter, it’s your personal credit profile and debt load that you can actually control to get a better rate.
What To Say and How To Handle Pushback
Once you have a representative on the line, be polite but get straight to the point. You don't need some elaborate script.
Kick it off with something simple and direct:
"Hello, I'm calling today to request a lower interest rate on my account. I've been a loyal customer for [number] years and have a history of on-time payments. A more competitive APR would really help me lower my financing costs."
If the first person you talk to says they can't help, don't hang up. Politely ask to speak with a supervisor or someone in the customer retention department. Those are the folks who usually have the authority to make changes to your account. For a deeper dive into negotiation tactics, check out our guide on how to negotiate discounts with your creditors.
And if you still get a hard "no"? Ask them to make a note of your request on your account. Sometimes, even a failed attempt can put you on the list for future promotional offers.
Using Digital Tools For Rate Reduction
Not a fan of phone calls? No problem. Many credit card companies now let you request an APR reduction right from their website or mobile app.
Poke around in sections like "Account Services" or "Card Benefits." It's usually a quick form that takes just a couple of minutes to fill out. While it's less personal, it's a super convenient, no-pressure way to see if you qualify for a lower rate.
The Long-Term Strategy: Improving Your Credit Score
At the end of the day, your most powerful weapon for reducing credit card interest rates for good is a killer credit score. It's the bedrock of your financial health. The higher your score, the less risky you look to lenders, which unlocks the absolute best rates and offers.
A huge piece of lowering your APR is understanding and actively improving your overall credit health. To do that, you need to laser-focus on the two biggest factors:
- On-Time Payments: Your payment history is a massive 35% of your FICO Score. Just one late payment can do serious damage. Set up autopay for at least the minimum amount so you're never, ever late.
- Credit Utilization Ratio: This one makes up 30% of your score. It’s simply how much credit you're using compared to your total limit. The golden rule is to keep it below 30% on every card and across the board.
By making these good credit habits part of your routine, you’re not just crossing your fingers for a lower rate—you're earning it. Over time, this makes every other strategy, from negotiation to balance transfers, that much more effective.
Using Balance Transfers and Personal Loans
Trying to negotiate with your current card issuer is a great first step, but let's be honest—sometimes the best move is to get your debt out of that high-interest environment altogether. This is where you can go on the offensive.
Two of the most effective tools for this are balance transfer cards and personal loans. Both can help you consolidate debt and seriously cut down what you're paying in interest, but they work very differently. Figuring out which one is right for you means looking past the flashy offers and into the fine print.
A well-planned balance transfer can feel like you’ve hit the pause button on interest, giving you a crucial window to attack the principal balance head-on.
This isn't just a minor tactic; it's a critical strategy in today's high-rate world. Recently, the amount consumers paid in credit card interest charges shot up by a staggering 52%, jumping from an already high $105 billion.
This wasn't because people were borrowing more—it was almost entirely due to rising APRs. Americans are now forking over an extra $55 billion in interest each year. That’s money that could have gone into savings, emergencies, or just paying the bills. You can dig into the full consumer credit card market report to see just how big this problem has become.
Mastering The Balance Transfer Strategy
The best balance transfer deals offer a 0% introductory APR for a limited time, usually somewhere between 12 to 21 months. This is a golden opportunity to stop the interest from piling up so every dollar you pay goes directly toward chipping away at the actual debt.
But to make this work, you need a solid game plan.
First, you have to account for the costs. Nearly every card charges a balance transfer fee, which is typically 3% to 5% of the amount you’re moving. So, if you transfer a $10,000 balance, a 3% fee instantly adds $300 to your new card. It's usually a small price to pay for months of 0% interest, but you absolutely have to factor it into your math.
Second, you need a payoff plan from day one. Take your total balance (including that fee) and divide it by the number of months in your 0% intro period. That number is your new monthly mission.
For example, if you move $10,300 ($10,000 + a $300 fee) to a card with an 18-month 0% APR offer, you need to pay about $572 every month. Sticking to that is non-negotiable if you want to be debt-free before the regular, much higher APR kicks in.
When a Personal Loan Makes More Sense
Balance transfers are fantastic, but they’re not for everyone. You typically need a good-to-excellent credit score (think 670 or higher) to get approved for the top-tier offers.
A personal loan might be a better fit if your debt is too large for the credit limit on a new card, or if you know you'll need more than 21 months to clear the balance. They offer a completely different structure that many people find more predictable for long-term debt repayment.
- Fixed Interest Rate: The rate on a personal loan is locked in. It won't change, unlike the variable rates on most credit cards.
- Predictable Payments: You get one fixed monthly payment for a set term, like 36 or 60 months. This makes budgeting so much easier.
- Installment vs. Revolving Debt: A personal loan is an installment loan—once it's paid off, the account is closed. For many, this helps break the cycle of revolving credit card debt for good.
Comparing Your Consolidation Options
So, which one should you choose? It really boils down to your specific financial situation: your credit score, how much debt you have, and how disciplined you can be with payments. If you're still weighing the pros and cons, our complete guide on how to consolidate credit card debt can help you make the final call.
At the end of the day, both balance transfers and personal loans are proactive moves. They shift you from playing defense against crushing interest rates to playing offense, letting you make real, measurable progress toward finally becoming debt-free.
Navigating Debt Relief and Settlement Options
When strategies like negotiation, balance transfers, and consolidation loans just aren't cutting it, it might be time to look into professional debt relief. This isn't about throwing in the towel; it's about bringing in an expert when the numbers no longer add up on your own.
One of the most common paths people take is debt settlement. This approach involves hiring a specialized company to negotiate with your creditors for you. Their one and only goal is to convince your creditors to accept a lump-sum payment that’s way less than what you actually owe.
How Debt Settlement Actually Works
The process is pretty straightforward, but it definitely requires commitment. Instead of sending payments to your creditors each month, you'll deposit a set monthly amount into a dedicated savings account that you control. As that account balance grows, your debt settlement company uses it as leverage to make settlement offers.
Once a creditor says yes to a deal, the funds are paid out from your account, and that debt is officially off your plate. This keeps happening, one debt at a time, until you're completely debt-free.
For a lot of people, this creates a clear, predictable finish line. A typical debt settlement program can get you out of debt in as little as 24 to 48 months—a timeline that feels like a fantasy when you’re just chipping away at high-interest balances with minimum payments.
The real magic of debt settlement is its potential to slash your total debt. Reputable programs often settle debts for a fraction of the original balance, which frees up your future income and provides a massive sense of relief.
This option is especially effective for unsecured debts like credit cards, old medical bills, and personal loans.
Understanding the Trade-Offs and Risks
While debt settlement can be a financial lifeline, you have to be honest about the downsides. To get the leverage needed for a good negotiation, you'll be advised to stop making payments to your creditors. This means you'll likely rack up late fees, get collection calls, and see a significant, negative hit to your credit score in the short term.
There are also tax implications to think about. The IRS sometimes sees forgiven debt as taxable income. If a creditor forgives $600 or more, they’ll probably send you a 1099-C form, and you might have to report that amount on your taxes.
Because of these moving parts, picking the right partner is critical to successfully reducing credit card interest rates and getting out of debt for good.
- Vetting is Key: Look for established companies with a solid track record and positive client reviews. You want someone who has done this a thousand times.
- Avoid Upfront Fees: Reputable debt settlement companies only charge a fee after they successfully settle a debt for you. If they ask for money first, run.
- Seek Transparency: A trustworthy partner will lay everything out on the table—the process, risks, costs, and timeline—before you ever sign anything.
Working with a vetted professional means you're not going through this stressful process alone. They handle the creditor calls, give you a structured plan, and help you navigate hurdles like credit score impacts and tax questions. They become your advocate, focused on getting you to the debt-free finish line as safely and efficiently as possible. For anyone feeling trapped, it can be the most direct route back to financial stability.
Bankruptcy: The Ultimate Financial Reset Button
When your debt feels so crushing that even the most aggressive strategies seem hopeless, it's time to look at the most powerful legal tool available for a financial fresh start: bankruptcy.
For many people, the word itself is terrifying. It's often tangled up with feelings of failure. But it's better to see it for what it is—a structured, legal path designed to give honest but unlucky people a real second chance.
Let's be clear: this isn't a decision you make on a whim. Filing for bankruptcy is a major legal move with long-term effects on your credit and finances. But when it's the right choice, it provides immediate relief from collection calls and wage garnishments while wiping the slate clean or restructuring what you owe.
Chapter 7 Bankruptcy: The "Clean Slate" Option
Often called "liquidation bankruptcy," Chapter 7 is the most common path for individuals. It’s built for people with limited income who simply don't have the means to pay back what they owe. A court-appointed trustee might sell some of your non-essential assets to pay back what they can to creditors.
Here’s what surprises most people: you can often keep your most important property. State and federal exemption laws are in place to protect things like:
- Your primary home (up to a certain amount of equity)
- A vehicle you need for work and daily life
- Retirement funds like a 401(k) or IRA
- Your household goods and personal belongings
Once the process is over, which usually takes about four to six months, the court issues a discharge order. This legally erases your responsibility to repay eligible unsecured debts—credit cards, medical bills, personal loans. It’s a true fresh start.
Chapter 13 Bankruptcy: The Reorganization Plan
What if you have a steady income but are still drowning? Chapter 13 might be a better fit. This is known as a "reorganization" or "wage earner's plan." It lets you bundle your debts into one affordable payment plan that lasts for three to five years.
You'll work with the court to create a plan. Instead of selling your assets, you make consistent monthly payments to a trustee, who then pays your creditors. It’s a structured way to get caught up on missed payments, especially for secured debts like your mortgage or car loan, all while being legally protected from creditors.
At the end of a successful Chapter 13 plan, any leftover eligible unsecured debt is usually discharged. This makes it a powerful choice for anyone who needs to protect their assets from foreclosure or repossession while still tackling their debt head-on.
Don't Go It Alone—This Requires Expert Guidance
Trying to decide between Chapter 7 and Chapter 13—or if bankruptcy is even the right move at all—is a heavy legal and financial choice. This is not a DIY project. The eligibility rules, the long-term credit damage, and the emotional toll make getting professional advice absolutely essential.
An experienced bankruptcy attorney will be your most important partner. They’ll do a deep dive into your income, assets, and debts to figure out which chapter you qualify for and which one actually helps you reach your financial goals. They cut through the jargon, handle the mountain of paperwork, and fight for you in court to make sure you get every protection the law offers.
This is a deeply personal decision. You can explore the key factors by asking yourself, "is bankruptcy right for me?". In the end, it’s about picking the path that gives you the best and most realistic shot at getting back on solid financial ground.
Common Questions About Lowering Your Credit Card Interest
Even with a clear game plan, it's totally normal to have a few questions rattling around in your head. Getting straight answers will give you the confidence to pick the right strategy for your situation and move forward.
Let's dig into some of the most common questions people ask once they learn about their options.
How Often Can I Ask for a Lower Interest Rate?
Generally, you can ask for a rate reduction every six to twelve months, especially if your financial picture has improved. Lenders want to see that you're becoming less of a risk.
The trick is to build a solid case for yourself. When you call, point to a history of on-time payments, a lower credit utilization ratio, or a jump in your credit score. If another card company sent you a better offer in the mail, use that as leverage. While there's no official penalty for asking too often, being strategic will seriously boost your chances of getting a "yes."
Pro Tip: Keep a simple log of when you called, who you spoke with, and what they said. This little bit of tracking helps you time your next request perfectly.
Will a Balance Transfer Hurt My Credit Score?
A balance transfer can cause a temporary dip in your credit score, but it's usually a net positive in the long run.
When you apply for the new card, the lender runs a hard inquiry, which might knock your score down by a few points for a little while. But the benefits almost always outweigh that tiny, temporary drop.
- Lower Utilization: Moving a big balance to a new card instantly drops the credit utilization on your old card, which is a huge factor in your score.
- More Available Credit: The new card also increases your total available credit, which helps lower your overall utilization ratio even more.
As long as you manage the new account responsibly—meaning you make every single payment on time—the long-term effect should be a good one. The real key is to resist the temptation to run up a new balance on that old, now-empty card.
Is Debt Settlement Better Than Bankruptcy?
One isn't "better" than the other—they're completely different tools for different levels of financial trouble. The right choice really comes down to your specific circumstances.
Debt settlement is all about negotiation. It's a solid option for people who can afford a structured monthly payment but simply can't pay back the total amount they owe. It offers a clear path to becoming debt-free without ever stepping into a courtroom.
Bankruptcy, on the other hand, is a formal legal process. It gives you broader legal protections and can often resolve debts much faster and more completely than settlement. A lot of people also wonder about the tax side of things; for instance, a common question is, "Can You Write Off Credit Card Interest?". Both bankruptcy and settlement have their own tax rules that you need to look at carefully. Because the stakes are so high, this isn't a decision to make alone. You'll want professional guidance from a vetted debt relief specialist or a qualified attorney.
What Is the Fastest Way to Lower My Interest Payments?
If speed is what you're after, two methods stand out, but which one works best depends on your credit.
The absolute fastest path is usually a 0% APR balance transfer card. To get the best offers, you'll need a good-to-excellent credit score (think 670 or higher). Approval can be almost instant online, and the transfer itself typically takes just 7 to 14 days. Just like that, your interest payments drop to zero for the entire promotional period.
Your next-fastest bet is simply calling your current credit card company and asking for a lower APR. If you have a solid payment history with them, a representative might be able to approve a rate reduction that takes effect immediately, all during that one phone call.
If you're feeling crushed by high-interest debt, you don’t have to go it alone. DebtBusters can connect you with a vetted debt relief professional for a free, no-obligation consultation to walk through your options. Find out how you can start your journey to becoming debt-free today.