

Being sued by a credit card company feels like a punch to the gut, but it's a legal notice you absolutely cannot ignore. Your first instinct might be to toss the papers aside and hope it goes away. Trust me, that's the worst thing you can do.
Ignoring a lawsuit pretty much guarantees a default judgment against you. That gives the creditor the green light to garnish your wages or freeze your bank account, often without any more warning.
What to Do When a Lawsuit Arrives
The moment a process server hands you that envelope, the clock starts ticking. It’s a scary experience, no doubt, but panic is your enemy. The key is to take a calm, methodical approach in the first 24-48 hours. This will protect your rights and set you up for a solid defense.
Right now, it’s not about legal strategy—it's about triage. Your only job is to figure out what you just received, who is suing you, and exactly how much time you have to respond.
First Look at the Summons and Complaint
Inside that envelope, you'll find two critical documents: the Summons and the Complaint.
Think of the summons as an official invitation to court that you can’t turn down. It will clearly state the deadline for filing a formal response, which is usually 20-30 days, depending on your state. This date is non-negotiable.
The complaint tells the story of why you're being sued. It will have numbered paragraphs, called allegations, that outline who the plaintiff is (the original credit card company or a debt buyer), the account in question, and how much they claim you owe. Read this carefully to make sure the debt is actually yours and the details look right.
Key Takeaway: The single most important piece of information on these documents is your response deadline. Mark it on your calendar, set a reminder on your phone—do whatever you have to do. Missing this date is the same as giving up.
This visual guide breaks down the essential first steps when you receive a lawsuit.
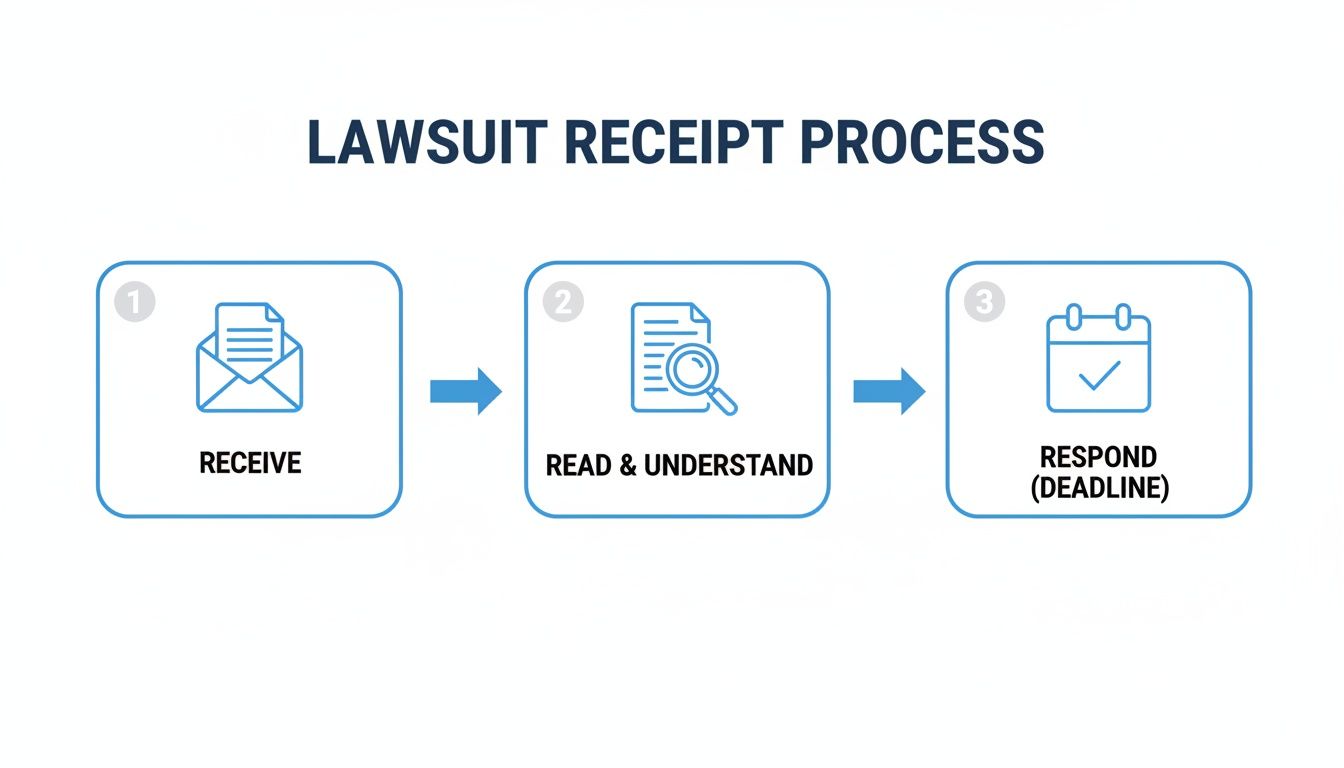
It really boils down to three simple but critical actions: get the documents, understand what they say, and respond before you run out of time.
Decoding Your Lawsuit Documents
To help you make sense of the legal jargon, here’s a quick-reference table breaking down the key parts of your summons and complaint.
| Document Component | What It Is | Why It's Critical |
|---|---|---|
| Summons | The official court notice that you are being sued. | It contains your non-negotiable response deadline (usually 20-30 days). Miss it, and you lose automatically. |
| Complaint | The document outlining the plaintiff's claims against you. | It lists the specific allegations, the amount owed, and who is suing you. This is what you must respond to. |
| Case Number | The unique identifier for your lawsuit in the court system. | You'll need this number to file documents, check your case status, or talk to the court clerk. |
| Plaintiff | The company or person suing you. | Verify if it's the original creditor or a third-party debt buyer you've never heard of. This can affect your defense. |
| Court Name | The specific court where the lawsuit was filed. | This tells you where to file your response and where any hearings will take place. |
Understanding these pieces is the first step in taking control of the situation.
Validating the Lawsuit
Before you do anything else, make sure the lawsuit is real. Look for a case number, the name of the court, and the judge's name. You can usually call the court clerk's office listed on the summons, give them the case number, and ask them to confirm that a lawsuit has officially been filed against you.
This is a crucial step. It protects you from scams and ensures you're dealing with a legitimate legal process, which is especially important if the plaintiff is a debt buyer you don't recognize.
The reality is, getting sued by a credit card company is becoming more and more common. Debt collection lawsuits have surged, with some studies showing that these types of cases have jumped by as much as 21% in a single year.
When a credit card company serves you with papers, learning how to respond to a lawsuit summons is the most important thing you can do to protect your finances. One of the strongest initial defenses is simply checking if the debt is too old to be collected. You can find out more by checking our guide on the https://debtbusters.com/statute-of-limitations-on-debt-by-state/.
How to Craft and File Your Legal Answer
Alright, this is where the rubber meets the road. Responding to the lawsuit with a formal document called an "Answer" is your first official move in court. This isn't just shuffling paperwork; it's your chance to push back, tell your side of the story, and lay the groundwork for your defense.
Ignoring the complaint is the equivalent of a forfeit—you automatically lose. So, getting this response drafted and filed is a non-negotiable step to protect yourself.
The Answer is basically your point-by-point reply to every single allegation the credit card company made in their complaint. You'll go through their numbered list and respond to each one. It sounds intimidating, but it really boils down to a few simple, strategic choices for each claim.
Structuring Your Response to Each Allegation
You generally have three ways to respond to each point the credit card company is making. How you answer each one is a strategic move that forces them to actually prove their case.
- Admit: Use this only for things that are 100% true and you can't possibly argue, like your name or address. Once you admit something, it's considered fact by the court.
- Deny: This is your go-to if a statement is flat-out wrong. When you deny an allegation, you force the plaintiff to come up with evidence to prove it. This is the most common response for things like the amount they claim you owe.
- State You Lack Sufficient Information: This is the right move when you honestly have no way of knowing if something is true. For instance, if a debt buyer you've never heard of is suing you, you have no knowledge of their records or if they even legally own the debt. This response has the same power as a denial.
Crucial Tip: When in doubt, it’s almost always safer to deny or state you lack information. Admitting something by mistake can seriously hurt your case down the line. This approach puts the burden of proof back on them, which is exactly where it belongs.
Raising Affirmative Defenses
Beyond just admitting or denying their claims, your Answer is where you get to go on the offensive by introducing affirmative defenses. These are legal arguments that could get the entire case thrown out—even if what they're saying about the debt is true.
Think of an affirmative defense as saying, "Even if I did owe this money, you still can't win because…" You have to raise these defenses in your initial Answer, or you might lose the chance to use them later on.
Some common affirmative defenses in these cases include:
- Statute of Limitations: The debt is simply too old, and the legal window to sue you for it has closed. These time limits vary a lot from state to state.
- Improper Service: They didn't notify you of the lawsuit correctly according to your state's laws.
- Lack of Standing: The company suing you (especially common with debt buyers) can't prove it has the legal right to collect this specific debt from you.
- Incorrect Amount: The total they're suing for is wrong because they've tacked on bogus fees, miscalculated interest, or failed to credit payments you made.
For a deeper dive, our guide on how to answer a summons for debt collection in Nevada has some great state-specific examples that can give you a better idea of how this works.
The Logistics of Filing Your Answer
Once your Answer is written, you have to follow a very specific legal process to get it filed. A mistake here can be just as bad as not responding at all. It comes down to formatting, serving, and filing.
- Formatting the Document: Your Answer needs to look like a legal document. It must have a "caption" at the top with the court's name, the case number, and the names of the plaintiff and defendant. Most local court websites have templates you can download and use.
- Serving the Plaintiff: This is a big one. Before you file with the court, you have to send a copy of your Answer to the lawyer who is suing you. This is called "service." Usually, you just mail it. Then you'll fill out a "Certificate of Service" form that confirms when and how you sent it.
- Filing with the Court Clerk: Finally, you take the original Answer, your Certificate of Service, and any filing fees to the court clerk's office. The clerk will stamp everything and officially add it to the case file. Always, always make copies of everything for your own records.
As you're putting your defense together, it's helpful to know about other procedural moves you might be able to make. Sometimes, you can argue that the case should be tossed out before it even gets started. You can learn more by reading about What Is a Motion to Dismiss in Arkansas?. Understanding these options gives you a much broader view of potential legal strategies.
Gathering Evidence and Building Your Defense
Alright, you’ve filed your Answer. The initial panic is over, and you’ve officially stepped into the ring. Now, the game changes. It’s less about reacting to their moves and more about building your own case, piece by piece.
This is the part where you start gathering every document tied to this debt. Your new mindset should be simple: make the company suing you prove every single claim they've made. You'd be amazed how often they simply can’t.
Creating Your Document Checklist
First things first, you need to get organized. The burden of proof is on them, but having your own records is your best weapon against their claims. Get a folder—physical or digital, whatever works for you—and start collecting everything.
Here’s what you should be looking for:
- The Original Credit Card Agreement: This is the contract that started it all. If you don't have a copy, don't sweat it. You can (and should) demand that they produce it as part of the legal process.
- All Account Statements: Hunt down every monthly statement you can find. These are gold for verifying the balance, tracking your payments, and spotting weird fees or interest charges.
- Records of Communication: Did you ever dispute a charge or ask for a payment plan? Dig up any emails, letters, or even notes from phone calls. Dates and details are your best friends here.
- Proof of Payments: Find any canceled checks, bank statements showing payments, or email confirmations. This is hard evidence that can poke holes in the total amount they claim you owe.
This isn’t just busy work. Each document helps you build a factual foundation to challenge their lawsuit. The more organized you are now, the easier it will be to find the cracks in their case later.
Expert Tip: Don't dismiss any document, no matter how small it seems. A single email where they agreed to a payment arrangement or a statement showing one incorrect fee can become a surprisingly powerful piece of evidence.
It's no surprise that these lawsuits are on the rise. As people face more financial pressure, credit card delinquencies have been climbing. The Federal Reserve Bank of St. Louis has pointed out that since mid-2021, the number of consumers more than 30 days late on their credit card bills has shot up, with some areas seeing a jump of over 40.6%. You can dig into the data yourself in this Federal Reserve Bank of St. Louis report. This economic strain is a direct pipeline to more lawsuits from credit card companies.
Identifying Your Strongest Defenses
Once you have your documents, you can start to pinpoint the legal arguments that will give you the most leverage. In credit card lawsuits, two of the most common and effective defenses are challenging the statute of limitations and the plaintiff's right to sue you in the first place.
Is the Debt Too Old to Collect?
Every state has a law called the statute of limitations, which sets a deadline for how long a creditor has to sue you over a debt. This time limit is usually between three and ten years, and the clock typically starts ticking from the date of your last payment.
If that deadline has passed, the debt is considered "time-barred." This is a knockout defense. If you can prove it, you can ask the court to dismiss the case entirely. You’ll need to look up your state's specific time limit and compare it to your records.
Can They Prove They Own the Debt?
Another killer defense is to challenge the plaintiff's standing. That's just a legal term for forcing them to prove they actually have the legal right to sue you for this specific debt.
This strategy is particularly powerful if you're being sued by a third-party debt buyer—a company that bought your old debt from the original credit card issuer, often for pennies on the dollar. These companies are notorious for having messy or incomplete paperwork.
To prove they have standing, they must show a clear "chain of assignment" that documents every time the debt was sold. If they can’t produce that unbroken chain of ownership, their case completely crumbles. Your job is to make them show their cards.
Exploring Your Options Beyond the Courtroom
Getting hit with a lawsuit is serious, but it doesn't automatically mean you're headed for a courtroom battle. Think of it more like a high-stakes negotiation tactic from the creditor. They've raised the pressure, but this also opens up several paths to resolve the debt—often without ever seeing a judge.
The key is to act strategically now that you have their full attention. These options can lead to much more manageable outcomes, saving you the stress and uncertainty of a drawn-out legal fight.
Negotiating a Settlement Directly
One of the most straightforward routes is to pick up the phone and negotiate a settlement yourself. You might be surprised to learn that the law firm suing you is often willing to talk. Their business model is built on collecting money efficiently, and a court case is expensive and time-consuming for them, too.
Your goal is to agree on a reduced amount, which you can pay either in a single lump sum or through a structured payment plan. A lump-sum offer is usually more attractive to them and can often get you a much deeper discount on the total amount you owe.
Start by contacting the attorney listed on the summons. Be polite, professional, and clear that you want to discuss settling the debt to avoid further litigation. That single phone call can shift the entire dynamic from adversarial to solution-oriented.
Crucial Reminder: Never agree to a settlement verbally. If you reach an agreement, insist on getting it in writing. The contract should detail the settlement amount, payment terms, and a statement that the debt will be considered fully satisfied. This document is your legal protection.
Using a Professional Debt Settlement Program
If the thought of negotiating on your own feels overwhelming, a professional debt settlement program is another solid option. With this approach, you hire a company whose experts negotiate with your creditors on your behalf. They already have established relationships with major creditors and their legal teams, which can be a huge advantage.
These professionals leverage their experience to aim for significant reductions in what you owe. The process usually involves making monthly payments into a dedicated account, which the company then uses to pay off the settlements as they're negotiated. This can be an effective way to handle a lawsuit while also tackling other outstanding debts you might have.
You're not alone in this. Total U.S. credit card debt has soared past $1 trillion, creating an enormous market for collection and settlement. The debt settlement industry itself was recently valued at $6.1 billion, a figure that's expected to grow—showing just how many people are in a similar spot. You can find more credit card debt trends on sellerscommerce.com.
Considering Debt Consolidation
For those juggling multiple high-interest debts on top of the one involved in the lawsuit, debt consolidation could be a lifeline. This strategy involves taking out a new, single loan to pay off all your other unsecured debts.
The benefits are pretty clear:
- One Monthly Payment: It simplifies your finances and makes it easier to stay on track.
- Lower Interest Rate: If your credit is decent, you might secure a lower interest rate than your credit cards, saving you money over time.
- A Clear Payoff Date: You'll have a defined timeline for when you'll be debt-free.
This approach works best if you have a steady income and a credit score good enough to qualify for a consolidation loan at a favorable rate. It can provide the funds needed to settle the lawsuit while getting your other debts under control at the same time.
When to Think About Bankruptcy
Finally, for situations involving truly overwhelming debt where other options just aren't realistic, bankruptcy provides a legal path to a fresh start. It’s a serious step with long-term credit implications, but it's a powerful tool designed to protect people from financial ruin.
There are two main types for consumers:
- Chapter 7 Bankruptcy: Often called "liquidation bankruptcy," this process can wipe out most unsecured debts, including credit card balances, in a matter of months.
- Chapter 13 Bankruptcy: This involves a court-supervised repayment plan that lasts three to five years. It's often used by people who have a regular income but need help restructuring their debts.
Filing for bankruptcy immediately triggers an "automatic stay," which legally halts the credit card lawsuit and all other collection activities against you. While it should be a last resort, it's an essential option to understand. You can explore a variety of alternatives to filing bankruptcy in our detailed guide to see what might work for you.
When facing a lawsuit, you have more power than you think. Let's break down how these different options stack up against each other.
Comparing Debt Relief Options
| Option | Best For | Potential Outcome | Key Consideration |
|---|---|---|---|
| Direct Settlement | Individuals comfortable negotiating and who can offer a lump-sum payment. | Pay a reduced, settled amount and have the lawsuit dismissed. | Requires strong negotiation skills and a written agreement is essential. |
| Debt Settlement Program | People with multiple debts who want professional help with negotiations. | Multiple debts are settled for less than the original amount owed. | Fees are involved, and it can temporarily impact your credit score. |
| Debt Consolidation | Those with good enough credit to qualify for a new loan with a lower interest rate. | One manageable monthly payment and a clear path out of debt. | Doesn't reduce the principal amount owed; requires discipline to avoid new debt. |
| Bankruptcy | Individuals with overwhelming debt that other options can't resolve. | Debts are discharged (Ch. 7) or restructured (Ch. 13); lawsuit is stopped. | A serious legal process with a significant, long-term impact on your credit. |
Each path has its own pros and cons, and the right choice depends entirely on your financial situation, your comfort level with negotiation, and your long-term goals. The important thing is to evaluate them carefully and choose the one that gives you the best chance for a fresh start.
What Happens If You Lose the Lawsuit
It’s critical to understand the stakes when a credit card company is suing you. Whether you don’t respond, can’t put together a defense, or the judge simply rules against you, the end result is the same: the court issues a judgment.
Think of a judgment as more than just a piece of paper. It’s a powerful court order that officially stamps the debt as legally enforceable. This gives the creditor a whole new set of tools to collect the money they say you owe.
Once that judgment is in place, the lawsuit is over, and the enforcement phase kicks in. This is where things get real, and the consequences can hit your finances hard and fast.
Understanding Wage Garnishment
One of the most common and jarring things a creditor can do with a judgment is garnish your wages. A wage garnishment is a court order sent directly to your employer, forcing them to withhold a chunk of your paycheck and send it straight to the creditor.
Your employer has no say in the matter; they have to comply. It’s a direct tap into your income before you even see it, which is why it’s such an effective collection tactic for creditors.
But they can’t take it all. Federal law puts a strict cap on how much can be taken. Under Title III of the Consumer Credit Protection Act (CCPA), the maximum they can garnish is the lesser of two amounts:
- 25% of your disposable earnings for that week.
- The amount your disposable earnings exceed 30 times the federal minimum wage.
"Disposable earnings" is what’s left after mandatory deductions like taxes. Some states offer even better protections that reduce these percentages, so it's smart to check your local laws.
How Bank Account Levies Work
A judgment also gives creditors the power to go after the money you already have. They can do this with a bank account levy, which lets them seize funds directly from your checking or savings accounts.
The process is surprisingly quick. The creditor’s attorney sends the levy order to your bank, and the bank is legally required to freeze your account. Then, they turn over your funds—up to the full judgment amount—to the creditor.
This can happen out of the blue, causing bounced checks and throwing your finances into chaos. It's a stark reminder of how much power a judgment gives a creditor.
Important Protection: Not all money can be taken. Certain funds are exempt, especially federal benefits. Money from Social Security, VA benefits, and federal student aid is generally protected from levies, as long as it’s direct-deposited into your account.
You Do Not Have to Go Through This Alone
Facing the threat of a wage garnishment or a bank levy is terrifying. The legal system feels confusing and stacked against you, especially when you’re being sued by a credit card company and your financial stability is at risk.
But here’s the good news: you still have options, and you don’t have to figure this out by yourself.
Expert help is available. A debt relief specialist or an attorney can step in, analyze your situation, explain your rights, and negotiate with the creditor for you—even after a judgment has been issued. They know the process inside and out and can often work out settlements or payment plans that are much more manageable than having your wages taken.
At DebtBusters, we connect people in your exact situation with vetted professionals who can help. Our network of debt relief experts is ready to give you the support and strategy you need to get back on your feet. You can get matched with a trusted partner for a no-obligation consultation to explore your options and find a clear path forward.
Common Questions About Credit Card Lawsuits
Getting sued by a credit card company throws a lot of scary questions into your head. The uncertainty alone is enough to keep you up at night, but getting straight answers is how you start taking back control. Let's tackle some of the biggest concerns right now.
Can You Be Arrested for Unpaid Credit Card Debt
Let's get this one out of the way immediately: you cannot be arrested or sent to jail just for not paying your credit card bill. In the United States, consumer debts are a civil matter, not a criminal one. The days of debtors' prisons are long gone.
The lawsuit you're holding is a civil action. That means the credit card company wants a court to order you to pay them money. It’s not about putting you behind bars. While you do have to follow court orders related to the lawsuit, losing the case has financial consequences, not criminal ones.
How Much Does a Lawyer Cost for a Debt Lawsuit
The cost of hiring an attorney for this kind of thing can be all over the map, but it’s probably more affordable than you think. Most consumer lawyers who specialize in these cases know their clients are in a tough spot financially, and they often structure their fees to reflect that.
You'll likely run into a few different payment models:
- Flat Fee: You pay one single price for them to handle the whole case. This is great for predictability because you know exactly what you're in for from the get-go.
- Hourly Rate: You’re billed for the time the lawyer spends on your case. This is pretty common but can feel a bit like a blank check.
- Contingency Fee: The lawyer only takes a fee if they win money for you. This is less common in debt defense cases unless you have a strong countersuit claim against the creditor.
- Affordable Payment Plans: Many firms will work with you, especially after they've negotiated your debt down and freed up some of your cash flow.
Don't let the fear of a huge bill stop you from at least asking for help. The vast majority of initial consultations are free, which gives you a chance to see what your options are without spending a dime.
Can I Still Settle the Debt After Being Sued
Absolutely. In fact, getting sued often makes it easier to settle. A lawsuit shows the creditor is serious, but it also means they're now paying their own lawyers. Most companies would rather get a guaranteed payment from a settlement than roll the dice and spend more money on a full-blown court battle.
You can start settlement talks at any point—right after you get the papers, after you file your Answer, or even on the courthouse steps. Calling the lawyer who is suing you to open a negotiation is a smart, proactive move that can end with you paying much less than what they're asking for in the lawsuit.
Key Insight: A lawsuit doesn't slam the door on negotiation; it usually throws it wide open. The single most important thing is to get any final settlement agreement in writing before you pay anything. That piece of paper is your proof that the debt is gone for good.
What if the Company Cannot Prove I Owe the Debt
This is where you might have some real leverage. The company suing you has the full burden of proof. If they can't produce the right documents to back up their claim, their case could completely fall apart.
To win, they have to prove two big things: that you actually owe the money, and that they are the ones who have the legal right to collect it. This is especially true if a debt buyer is suing you; they need to show a clean "chain of custody" from the original bank.
If they're missing key paperwork—like the original cardmember agreement you signed or a complete history of payments—you can challenge their entire case. A strong challenge on these grounds can lead to the judge dismissing the lawsuit completely.
Facing a lawsuit is a serious wake-up call, but it's not the end of the road. You have more power here than you realize. DebtBusters can connect you with experienced debt relief pros who can look at your specific situation and lay out a clear path forward. Get a free, no-obligation consultation today.